Medicare vs. Employer Coverage in Your Early 60s in Michigan: A Practical Guide for Working Adults
A clear, step-by-step guide to help Michigan employees approaching 65 compare employer group health plans with Medicare Parts A, B, and D — covering costs, networks, prescriptions, enrollment timing, and when to stay, switch, or combine coverages.
Why this decision matters if you’re still working
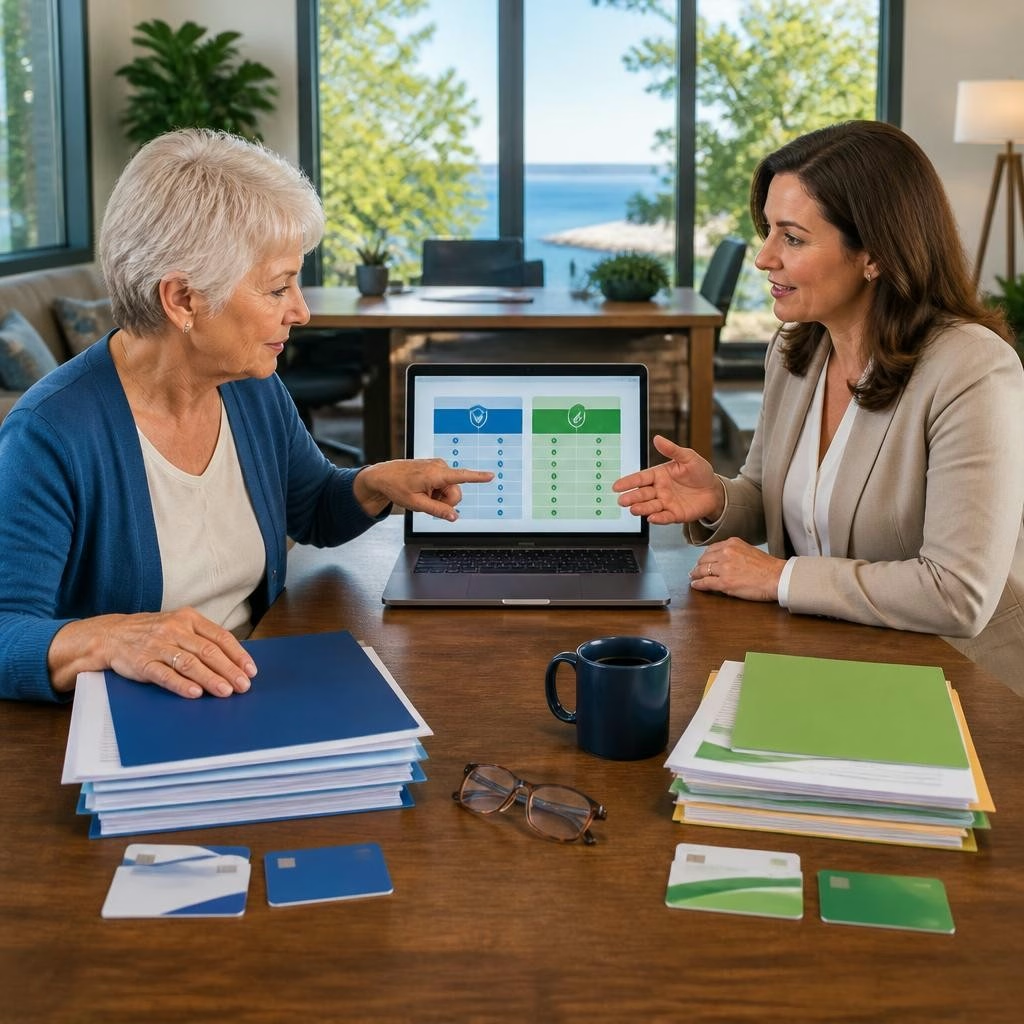
Turning 65 while still employed brings an important benefit — choice. You may be able to keep your employer group health plan, enroll in Medicare, or use both together. Each path affects monthly costs, who pays first, provider access, prescription coverage, and your long‑term planning. In Michigan — whether you work in Troy, Metro Detroit, or elsewhere in the state — making the right choice now can avoid penalties, reduce unexpected out‑of‑pocket costs, and keep your preferred doctors on your care team.
Quick refresher: What Parts A, B and D cover
Medicare Part A generally covers inpatient hospital care and is often premium‑free for people who paid Medicare payroll taxes. Part B covers outpatient services, doctor visits, and durable medical equipment and usually charges a monthly premium. Part D covers prescription drugs and is sold as standalone plans or included in many Medicare Advantage (Part C) plans. Original Medicare (Parts A and B) does not include prescription coverage unless you add Part D, and it does not have the same kind of annual out‑of‑pocket maximum found in most Medicare Advantage plans.
Core comparison points: what to gather before you decide
Collect these items from your employer and Medicare options to compare apples to apples: (1) employer premium contribution and your payroll deduction; (2) deductibles, copays and coinsurance; (3) provider network and whether your primary doctors and specialists participate; (4) prescription drug formulary and tiers plus whether the employer plan is labeled 'creditable' for Part D; (5) out‑of‑pocket maximums and coverage caps; and (6) any retiree or retiree‑subsidy provisions. Having a one‑page list of current prescriptions and the providers you use makes comparisons far easier.
Employer size and enrollment timing: key Michigan rules to know
A pivotal factor is whether your employer has 20 or more employees. For employers with 20+ staff, the group plan typically remains primary and you can usually delay Part B without incurring a late‑enrollment penalty, signing up during a Special Enrollment Period (SEP) once employment or coverage ends. If your employer has fewer than 20 employees, Medicare often becomes primary at 65 and you may want to enroll in Part B when first eligible. In all cases, confirm deadlines with your HR department: you generally have an SEP (commonly 8 months) to enroll in Medicare after employer coverage ends to avoid penalties. Employers must also notify you whether their prescription coverage is creditable for Part D — keep that notice.
What to watch with prescription coverage
Prescription coverage is often the deciding factor. If your current employer plan covers the drugs you take at acceptable copays and is considered creditable, you may delay Part D without penalty. If it is not creditable, enrolling in a Part D plan when first eligible avoids permanent late‑enrollment penalties. Compare formularies carefully: a drug that’s inexpensive under your group plan could be costly under some Part D or Medicare Advantage formularies. Bring your medication list to every comparison and check prior authorization and step therapy rules.
When staying on employer coverage makes sense — and when switching helps
Staying on your employer plan can make sense if your employer pays a significant portion of the premium, your doctors are in the network, and prescription costs are low. Switching to Original Medicare plus Part D (and possibly a Medigap policy) may be preferable if your doctor doesn’t accept your employer plan or if Medicare options lower your total annual cost even after premiums. Some people choose a blended approach — enrolling in Part A (which is often premium‑free) while delaying Part B if employer coverage is primary — then adding Part B after retirement. Each scenario depends on employer size, costs, networks and your medical needs.
A practical, step‑by‑step checklist to compare options
1) Request a benefits summary and prescription drug creditable coverage notice from HR. 2) List your top providers and medications. 3) Get quotes for Medicare Part B and Part D plans that serve your ZIP code (Troy and surrounding areas may have several carriers and Medicare Advantage choices). 4) Total your likely yearly spend: premiums (employer share and yours), deductibles, copays, expected prescriptions and any balance‑billing risk. 5) Ask whether your employer offers retiree coverage or subsidies tied to staying on the group plan. 6) If unsure, consult a licensed expert who can model costs and network access for your situation.
How Lifeguard Insurance Services can help — and next steps
At Lifeguard Insurance Services in Troy, MI, we specialize in Social Security and Medicare planning and work with local partners like HAP and BCBS MI to tailor choices to Michigan residents. Our team is known for patient, thorough explanations and quick responsiveness — clients consistently say staff walk them through options without feeling rushed — and we focus on finding plans that include preferred doctors and save money where possible. If you want a guided, Michigan‑specific comparison, bring your benefits summary and prescription list and we’ll run side‑by‑side scenarios to show the real cost and provider implications. Ready to safeguard your family's future? Contact Lifeguard Insurance Services today for a free, no‑obligation quote and personalized coverage advice—let's protect what matters most!
Customer review
Article by
Lifeguard Insurance Services
The Lifeguard Agency specializes in Social Security Planning, Medicare, Annuities, and Age-Specific Insurance Plans. Whether you’re a Gen X just starting to think about Social Security, or a Baby Boomer sorting through too many Medicare plans, The Lifeguard Agency is here for you. We utilize the latest technology and strong relationships with local partners like HAP and BCBS MI to tailor a long-term healthcare strategy that meets the unique needs of you and your family. You’ve lived a life that’s earned respect, and we’re here to provide it. That’s why we take a cost-conscious, fee-slashing approach to your planning, helping you put more of your hard-earned dollars toward the long, fulfilling retirement you deserve.