Life Insurance for Gen X in Michigan: Protecting Your Home, Kids’ College, and Retirement
Practical guidance for Michigan Gen X homeowners who are funding mortgages and college while planning retirement — how to size and structure life insurance to cover debts, education, and income needs without overspending.
Why Gen X faces unique life insurance choices now
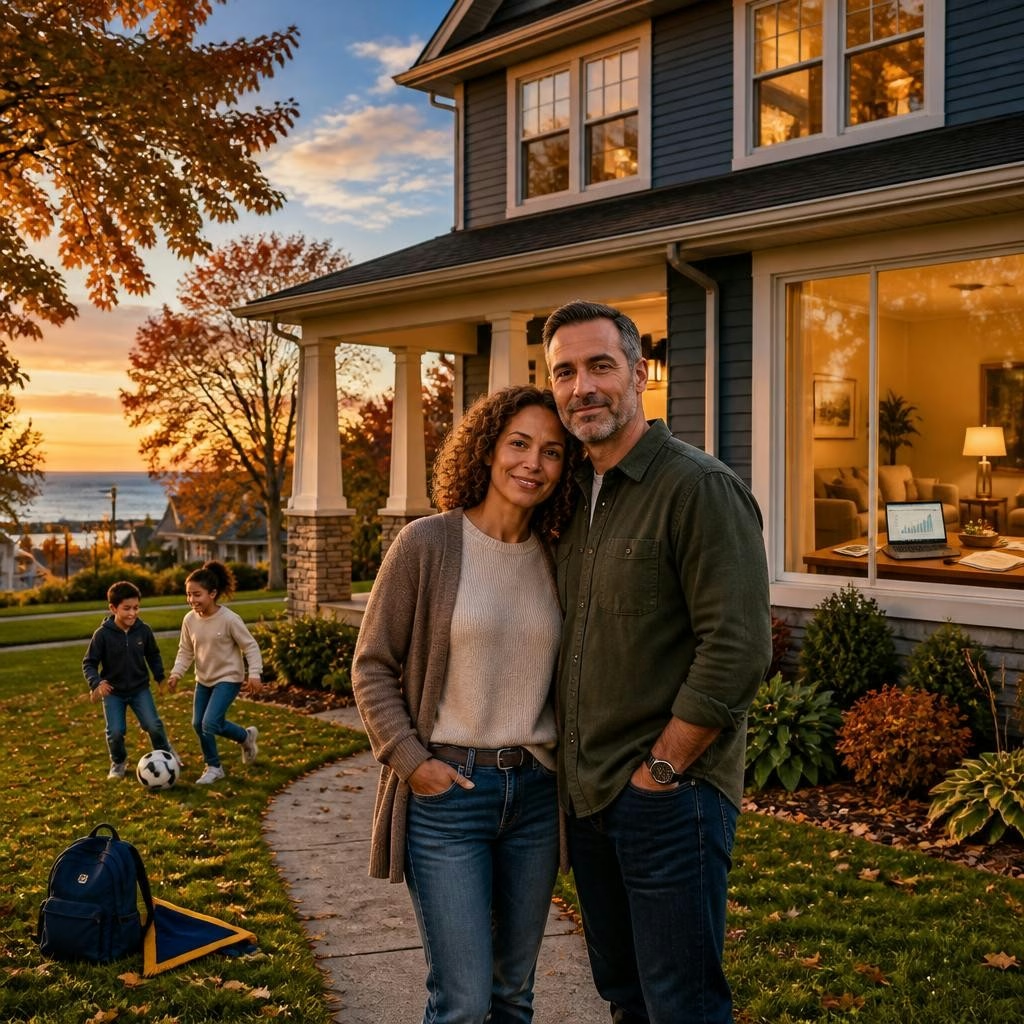
Many Gen X households in Michigan are juggling three major financial priorities at once: mortgage obligations, paying for children’s education, and building retirement savings. That combination creates a different insurance need than a younger household or someone nearing retirement. Life insurance for Gen X is less about speculative wealth transfer and more about providing targeted protection — covering outstanding debt, securing a child’s education plan if needed, and replacing income so retirement goals remain on track.
Core goals your life insurance should address
When you evaluate coverage, focus on three concrete goals: 1) pay off or reduce remaining mortgage debt so your family isn’t forced to move, 2) preserve the ability to fund expected college costs or substitute scholarships/loans if needed, and 3) replace critical income so your spouse can maintain living expenses and continue retirement contributions. Prioritizing these outcomes helps avoid over-insuring or buying a product that doesn’t match the timeline of your obligations.
Common policy types and how they fit Gen X plans
Term life remains the most cost-effective option to cover time‑bound needs — for example, a 15- or 20-year term matched to remaining mortgage years or until children finish college. Permanent policies (whole or universal) build cash value and can serve estate-planning or lifelong liquidity needs, but they cost more and often aren’t the best vehicle if your primary concern is mortgage and college protection. A hybrid approach — term for large, temporary obligations and a modest permanent policy for long-term needs — is frequently a sensible balance.
Step-by-step method to size your coverage
A practical sizing approach: 1) List outstanding mortgage balance and expected years until it’s paid. 2) Estimate remaining education funding you want to guarantee (consider in‑state options, scholarships, and expected family contribution). 3) Calculate income replacement: decide how many years of gross income would be needed to cover living and retirement contributions until your planned retirement age. 4) Add a reserve for final expenses and short-term liquidity. 5) Subtract liquid savings and other protections (spouse’s income, existing policies) to find the net need. This creates a defensible target rather than an arbitrary multiple of income.
Strategies to keep premiums affordable
To protect all three priorities without overspending, consider: 1) laddered term policies that expire when particular obligations end (mortgage, college), 2) lower-cost term coverage sized specifically for debt and education while using retirement savings to cover longer-term income needs, and 3) reviewing riders only when they fill a specific gap. Also revisit coverage as mortgage balances shrink or children become financially independent — downsizing a policy can be a smart, cost-saving move. Lifeguard Insurance Services emphasizes cost-conscious planning, which aligns with these approaches.
Michigan-specific factors to keep in mind
Local context matters: underwriting and premium pricing reflect your health history and age, so acting sooner rather than later can lock in better rates. Michigan residents should also consider how local college choices (in-state tuition opportunities) and the region’s housing market affect how much protection you need. For families coordinating health and long-term care planning, Lifeguard’s relationships with regional partners such as HAP and BCBS MI can be part of a broader financial-health strategy when assessing long-term household costs.
How Lifeguard Insurance Services supports Gen X decision-making
Working with an agent who translates numbers into practical plans removes a lot of stress. Lifeguard’s clients consistently highlight clear explanations, responsiveness, and personalized care — with one reviewer specifically noting the team’s dedication and willingness to go above and beyond. Expect an initial review of mortgage and education timelines, a clear presentation of term vs. permanent options, and a recommendation tailored to your budget and goals rather than a one-size-fits-all sale.
Next steps — a checklist and how to get started
Checklist: gather mortgage payoff figures, recent pay stubs and household income, current college savings balances, and a list of existing policies. Schedule a planning session to run through the sizing steps above and review quotes for targeted term coverage and any permanent options you’re considering. Ready to safeguard your family's future? Contact Lifeguard Insurance Services today for a free, no-obligation quote and personalized coverage advice—let's protect what matters most!
Customer review
Article by
Lifeguard Insurance Services
The Lifeguard Agency specializes in Social Security Planning, Medicare, Annuities, and Age-Specific Insurance Plans. Whether you’re a Gen X just starting to think about Social Security, or a Baby Boomer sorting through too many Medicare plans, The Lifeguard Agency is here for you. We utilize the latest technology and strong relationships with local partners like HAP and BCBS MI to tailor a long-term healthcare strategy that meets the unique needs of you and your family. You’ve lived a life that’s earned respect, and we’re here to provide it. That’s why we take a cost-conscious, fee-slashing approach to your planning, helping you put more of your hard-earned dollars toward the long, fulfilling retirement you deserve.