Health Insurance for Michigan Small Business Owners and Self‑Employed Professionals: A Troy‑Area Guide
Practical, Michigan‑focused guidance on individual plans, association options, HSAs, and cost‑management strategies for Troy-area entrepreneurs and freelancers — plus how a local agency can help you choose and enroll confidently.
Why health coverage matters for Michiganders who run their own business
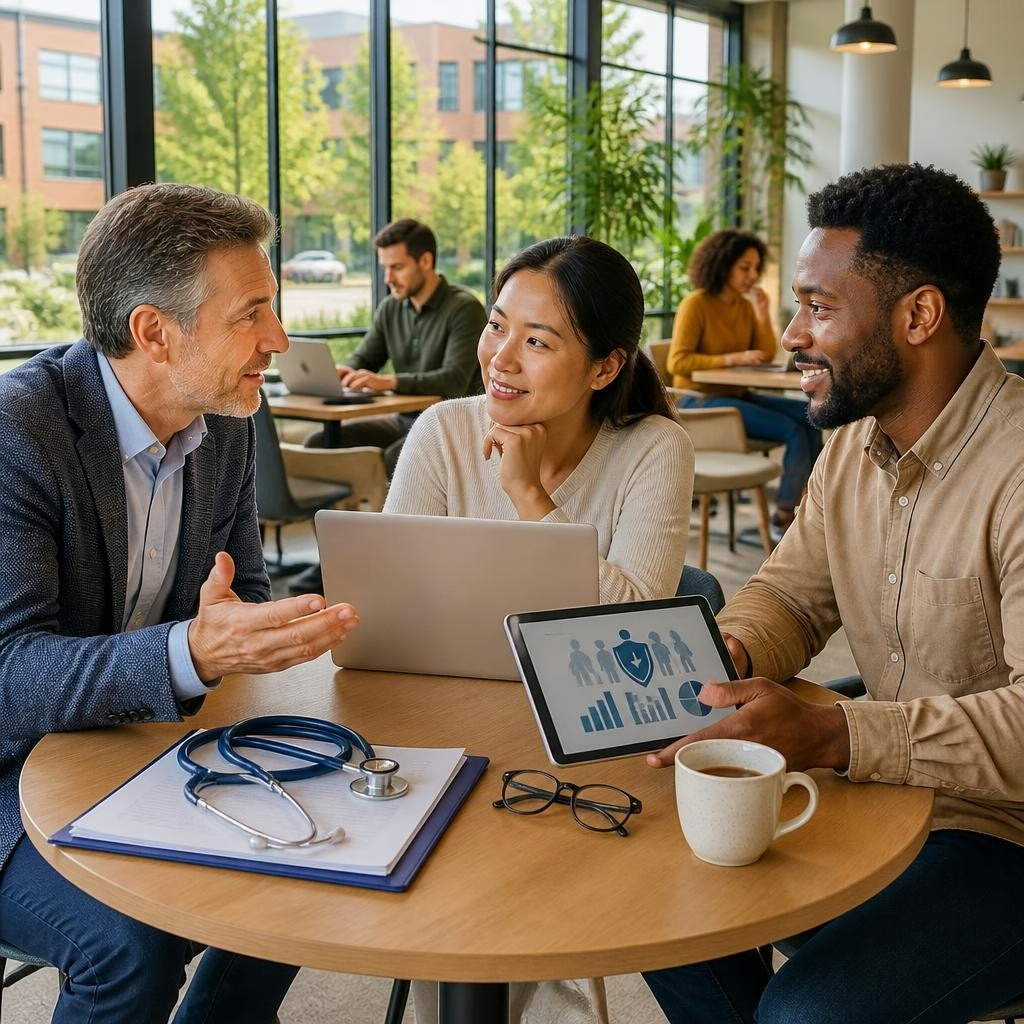
Running a small business or working as a self‑employed professional in Troy or elsewhere in Michigan means juggling unpredictable income and busy schedules. The right health coverage protects your personal finances if you get sick, keeps you compliant with regulations, and reduces stress so you can focus on growing your business. Unlike employer‑sponsored plans, independent options require you to compare networks, deductibles, and cost‑sharing — but they also offer flexibility that can better match the needs of solo entrepreneurs and small teams.
Primary coverage routes: individual Marketplace and private plans
Most self‑employed people start by comparing the ACA Marketplace (Health Insurance Marketplace) with off‑exchange private plans. The Marketplace is where you’ll see eligibility for premium tax credits (if you qualify), and it’s also the place to enroll during Open Enrollment or after qualifying life events. Off‑exchange plans can offer different networks or features and may be worth comparing when you don’t qualify for subsidies. In all cases, review provider networks, prescription coverage, and the total expected annual cost (premiums plus likely out‑of‑pocket expenses), not just the monthly premium.
Association plans and alternatives that can offer group‑style benefits
Some professional associations, trade groups, or industry organizations provide access to group‑style health coverage for members. These association plans can sometimes reduce administrative burdens or provide broader networks than individual policies. Availability and eligibility vary, so check whether a relevant Michigan association or local business group offers plans for your profession. If you employ people, even part‑time, investigate small‑group options as your business grows — group plans often spread risk and can lower per‑employee costs.
Health Savings Accounts (HSAs) and other tax‑advantaged tools
Pairing a qualifying High Deductible Health Plan (HDHP) with an HSA can be an effective strategy for self‑employed individuals who want to save on taxes and build a health expense cushion. Contributions to an HSA are pre‑tax (or tax‑deductible), grow tax‑free, and can be used for qualified medical expenses. For short gaps in coverage, tools like COBRA or short‑term solutions exist, but they have limitations — your agent can help you compare continuity options against Marketplace plans to find the best financial fit.
Practical strategies to keep premiums manageable while protecting income
Controlling health costs is about more than picking the cheapest premium. Consider a plan with a narrower network if your preferred local providers are included, use telehealth options for routine care, and maximize preventive services that keep overall costs lower. For income protection, review disability insurance (available through Lifeguard’s services) to replace wages if you can’t work. Bundling coverages thoughtfully — for example coordinating health, disability, and life insurance — can reduce overlap and simplify bills.
How a Troy‑based agency can make the process easier
Working with a local agency removes much of the complexity. Lifeguard Insurance Services leverages relationships with Michigan carriers like HAP and BCBS MI and uses current technology to compare options side‑by‑side, helping you see total costs and provider networks clearly. Clients consistently praise the team’s clarity and responsiveness; one recent client specifically noted that an agent walked them through multiple proposals and ensured they understood each option. That hands‑on guidance is especially useful when you’re balancing business planning and family needs.
A step‑by‑step checklist for choosing the right plan
1) Inventory your healthcare needs: list dependents, regular prescriptions, and preferred providers. 2) Estimate your budget: include premiums, expected medical visits, and potential deductibles. 3) Check networks and pharmacy coverage to avoid unexpected out‑of‑network costs. 4) Compare total annual costs, not just monthly premiums. 5) Evaluate HSA eligibility and disability coverage for income protection. 6) Ask about association plans or employer‑sponsored options through spouse or partners. 7) Get help from a licensed agent to compare proposals and confirm enrollment details, then schedule an annual review to adjust coverage as your business changes.
Next steps and a clear call to action
If you’re a Troy‑area entrepreneur or freelancer ready to compare options and protect both your health and income, a local, experienced agent can save you time and help you make confident choices. Ready to safeguard your family's future? Contact Lifeguard Insurance Services today for a free, no-obligation quote and personalized coverage advice—let's protect what matters most!
Customer review
Article by
Lifeguard Insurance Services
The Lifeguard Agency specializes in Social Security Planning, Medicare, Annuities, and Age-Specific Insurance Plans. Whether you’re a Gen X just starting to think about Social Security, or a Baby Boomer sorting through too many Medicare plans, The Lifeguard Agency is here for you. We utilize the latest technology and strong relationships with local partners like HAP and BCBS MI to tailor a long-term healthcare strategy that meets the unique needs of you and your family. You’ve lived a life that’s earned respect, and we’re here to provide it. That’s why we take a cost-conscious, fee-slashing approach to your planning, helping you put more of your hard-earned dollars toward the long, fulfilling retirement you deserve.